Is NAB cutting fixed-rate home loans a sign interest rates have peaked?
- NAB has cut two- and three-year fixed home loan rates
- It's the first major bank to cut fixed rates for some months, amid five increases to the cash rate in 2026
- It comes the day after the jobless rate recorded a worse-than-expected 4.9%
- That prompted markets to declare interest rates have peaked
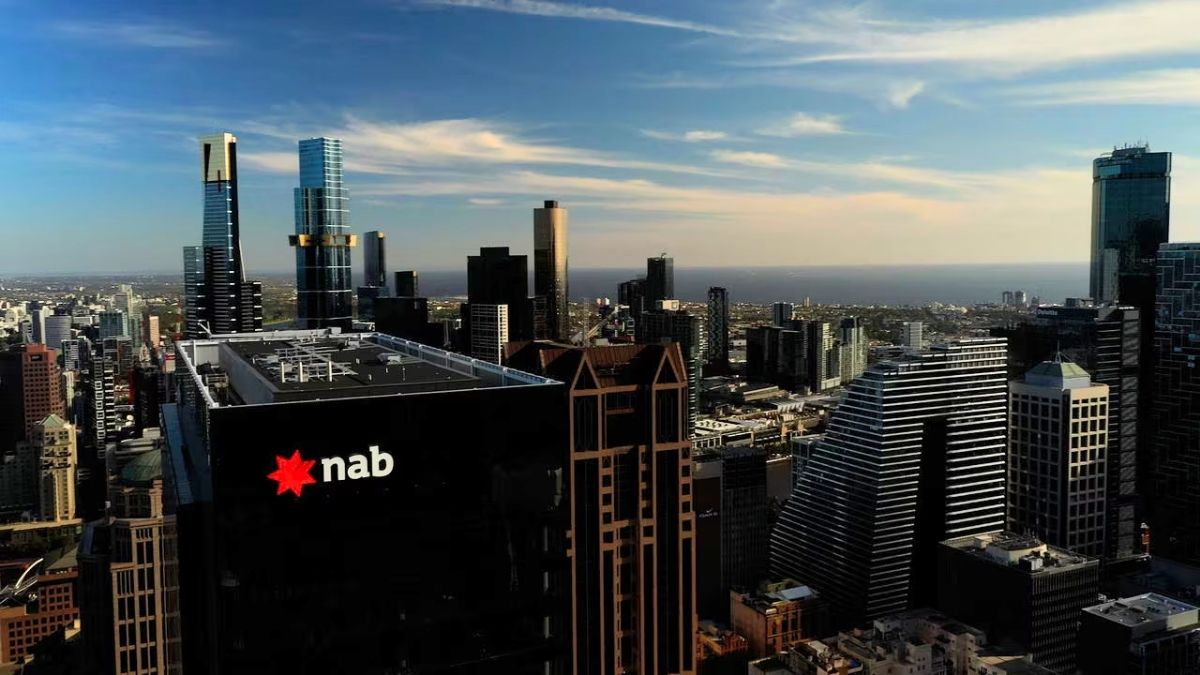
NAB has cut up to 28 basis points off its range of two- and three-year fixed-rate home loans, signalling an early vote of confidence the official cash rate will be heading lower.
NAB has reduced both owner-occupier and investment home loan rates, cutting its lowest rate to 6.64% p.a. for loan-to-value ratios (LVRs) 80% and under.
Here are the new rates for owner-occupier home loans with principal and interest (P&I) repayments:
Two-year fixed
| LVR | Interest rate (% change) | Comparison rate* |
| 60% or less | 6.64% p.a. (-0.17%) | 7.28% p.a. |
| 60.01%-70% | 6.64% p.a. (-0.17%) | 7.28% p.a. |
| 70.01%-80% | 6.64% p.a. (-0.17%) | 7.44% p.a. |
| 80.01% or more | 6.74% p.a. (0.17%) | 7.46% p.a. |
Three-year fixed
| LVR | Interest rate (% change) | Comparison rate* |
| 60% or less | 6.64% p.a. (-0.28%) | 7.22% p.a. |
| 60.01%-70% | 6.64% p.a. (-0.28%) | 7.22% p.a. |
| 70.01%-80% | 6.64% p.a. (-0.28%) | 7.36% p.a. |
| 80.01% or more | 6.74% p.a. (-0.28%) | 7.39% p.a. |
NAB is the first major bank to cut fixed home loan rates after months of rising interest rates on the back of five cash rate increases in 2026.
Its two- and three-year fixed home loan rates are now the lowest among the big four banks.
Why is NAB cutting fixed home loan rates?
NAB's move comes a day after shock jobs data that put the unemployment rate at 4.9%, well above market and Reserve Bank forecasts.
It was driven by the loss of 44,000 jobs in October after almost 40,000 were shed in September, marking a considerable cooling of the jobs market.
The rate also arrived around 12 months earlier than the Reserve Bank had forecast, stoking fears the economy is heading into a sharp downturn and prompting markets to declare the 4.85% cash rate is the peak of the current upcycle.
Not surprisingly, NAB economists agree and on Friday announced they expect unemployment will spike higher at 5.5% by early 2028.
Will home loans fall lower?
The RBA's monetary policy board is due to meet on 7-8 December to consider where to leave the cash rate until its first meeting in 2027 in February.
It's widely tipped the board will keep the cash rate on hold given the worse-than-expected jobs figures but there will also be October inflation data to consider, due to be released on Wednesday.
The Consumer Price Index headline figure is forecast to climb to 4.7% in October, up from 4.3% in September.
Underlying inflation - when extreme price swings are stripped out - is expected to be steadier, around 3.6% year-on-year, the same as the September figure.
The Reserve Bank is likely to find itself in the unenviable economic position of balancing rising unemployment with rising inflation, while also trying to avoid tipping Australia into recession.
It's prompted some economists to bring forward their forecasts of a cut to the cash rate to August 2027.
Bond markets are now fully priced for a cut by September.
Should I fix my home loan rate?
For now, NAB's new fixed home loan rates remain above the lowest variable-rate home loans on the market.
With analysts widely forecasting the next move in the cash rate will be lower, many borrowers will likely opt for variable rates in a bid to ride the expected interest rate downcycle.
See also:
- How to choose between a fixed-rate or variable-rate home loan?
- Should you fix your home loan interest rate?
Now that NAB has moved to cut select fixed rates, other lenders may be prompted to do the same in the interests of competition.
The only other bank to reduce fixed home loan rates this month is member-owned Unity Bank, cutting 15 basis points from its fixed rates on 12 November.
Other lenders may be prompted to dangle some bait to compete for new business amid the collapse of Australia's home lending market, hit hard by 2026's five cash rate increases and property investment tax changes announced in the May federal budget.
See also: Investor lending smashed by government tax changes
Australia's property market is seeing its steepest decline in 40 years, with the sharp downturn in capital city values now widening to regional markets.
Property analyst Cotality has described the current market as "a buyers' market with no buyers".
Advertising
Buying a home or looking to refinance? The table below features home loans with some of the lowest interest rates on the market for owner occupiers.
| Lender | Home Loan | Interest Rate | Comparison Rate* | Monthly Repayment | Repayment type | Rate Type | Offset | Redraw | Ongoing Fees | Upfront Fees | Max LVR | Lump Sum Repayment | Extra Repayments | Split Loan Option | Tags | Features | Link | Compare | Promoted Product | Disclosure |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
6.34% p.a. | 6.34% p.a. | $3,108 | Principal & Interest | Variable | $0 | $0 | 75% |
| Promoted | Disclosure | ||||||||||
6.39% p.a. | 6.30% p.a. | $3,124 | Principal & Interest | Variable | $0 | $0 | 80% |
| Promoted | Disclosure | ||||||||||
6.39% p.a. | 6.42% p.a. | $3,124 | Principal & Interest | Variable | $0 | $0 | 60% |
| Promoted | Disclosure | ||||||||||
6.42% p.a. | 6.42% p.a. | $3,134 | Principal & Interest | Variable | $0 | $395 | 60% | Disclosure |