- Earned wage acess (EWA) lets workers get hold of their wages as they earn them.
- EWA platforms typically charge a flat fee per withdrawal, often subsidised by the employer.
- EWA arrangements are already huge in the US and UK and more and more Australian employers are starting to offer one.
Most people are familiar with the struggle of being paid fortnightly or even monthly and having to manage your expenses until payday rolls around. According to independent research commissioned by Paytime, 81% of Australians would like to access their earned pay before payday, and some of them might be able to do so using earned wage access platforms.
What is earned wage access?
Earned wage access (EWA) allows workers to access their wages as they earn rather than waiting for payday.
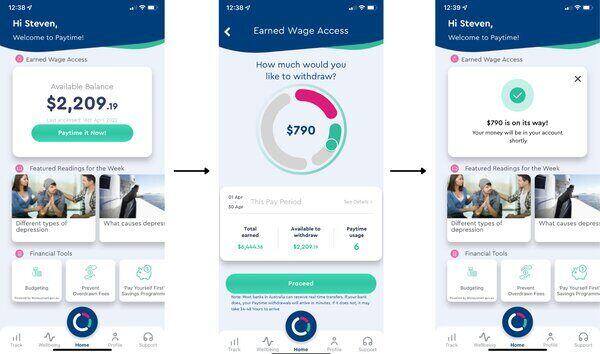
Say you're paid $25 an hour after tax and work 80 hours a fortnight. Each Wednesday you're paid $2,000 for the previous two weeks' worth of work. Using EWA, you could claim $1,000 halfway through the pay cycle, and just have your wages reduced.
"Up until now, if Australians have needed extra money for an unexpected expense the only solutions they’ve had are payday loans, buy now pay later options or credit cards – and they are all putting people into debt," Steven Furman, CEO of earned wage access provider Paytime, told Savings.com.au in 2022.
"One thing we can’t change in life is that there are always going to be unexpected expenses crop up no matter how good you are at budgeting.
"Earned wage access gives employees access to their own money to pay for these things so they don’t have to borrow it from somewhere else.”"
Amid the rising cost of living crisis, EWA has become an increasingly attractive option for thousands of employees living paycheck to paycheck.
It’s important not to confuse EWA with credit cards, payday loans, and pay in advance apps - there is no lending involved so there's no interest rates, late fees, nor credit checks.
“There’s a bit of confusion here about our product, we are not a pay-in-advance app or a payday loan. We’re actually the opposite as there’s nothing for a person to pay back," Mr Furman said.
How does it work?
An earned wage access provider such as Paytime partners with an employer to offer employees access to a percentage of earned income. This typically ranges from about 20-50% of their pay. To do this, the EWA provider will integrate into the employer's existing payroll software and HR management systems. From there, employees are able to track and access their pay whenever they need to via an app. If an employee chooses to withdraw money, they will receive it within minutes (if their bank supports OSKO payments) or within 24-48 hours otherwise.
Any withdrawals made by employees are then taken into account during payroll reconciliation.
How to get hold of earned wage access
Although, as an employee, you may be eager to have the option to withdraw money before your paycheck, it’s up to your employer to introduce it to staff. If your company isn't partnered with an earned wage access platform, you won't be able to use the service so it's something worth asking about when you're job hunting.
How much does it cost?
According to Paytime, there are several models an employer can choose to implement:
For employers, the first option is not having to pay for anything (it’s free), but that means it will cost staff an ATM style fixed fee every time they withdraw their earned wage
The second option is where the employer chooses to cover the fee themselves and make it free for staff to make the withdrawals
The final option is sharing the ATM style cost between both parties (subsidy model)
Savings.com.au's two cents
Lots of people struggling between pay cheques turn to payday loans to make ends meet. These products often have huge interest rates and fees, and can be the start of a debt spiral where you're borrowing to pay off your existing loans. That's not what earned wage access is. You aren't borrowing money, just accessing money that you've already earned.
If your employer subsidises the cost of withdrawing your wages, there isn't really a downside to using these services, but make sure you check that. Should you need to pay the withdrawal fee yourself, while it's probably a better option than a payday loan it's still not a great habit to get into and you might be better off trying to budget so you can get to your next payday without having to pay the fee.
Who uses earned wage access?
While EWA is still relatively new to Australia, US companies such as PayPal, Walmart, McDonalds, Uber, Hilton, and Unilever provide the feature to their employees. In fact, 80% of the Fortune 200 companies now offer EWA.
Here in Australia, companies such as McGrath Estate Agents, Supabarn supermarkets, and Aspen Pharmacare have been the first to jump on board the EWA train.
"Another myth about our product is that it’s only for lower income earners. We have many users on six figure salaries," Mr Furman said.
"Some choose to access their wage early to pay down their mortgage faster, others use it to manage cash flow while waiting for company expense reimbursements or others use it to take advantage of investment opportunities."